A missed reconciliation rarely looks urgent on the day it happens. A few uncategorized expenses, a customer payment posted late, and a bank feed left unchecked can quietly turn into an unreliable profit-and-loss statement at the end of the month. For owners already managing customers, payroll, and growth, a remote bookkeeping assistant for small business creates the consistent financial rhythm that prevents those small gaps from becoming expensive decisions.
This is not about handing your finances to an anonymous contractor for occasional data entry. The right remote bookkeeper becomes a dedicated part of your operating routine: maintaining clean records, preparing information your accountant can use, and making it easier to see what is happening in the business before a tax deadline or cash crunch forces the issue.
What a Remote Bookkeeping Assistant Can Handle
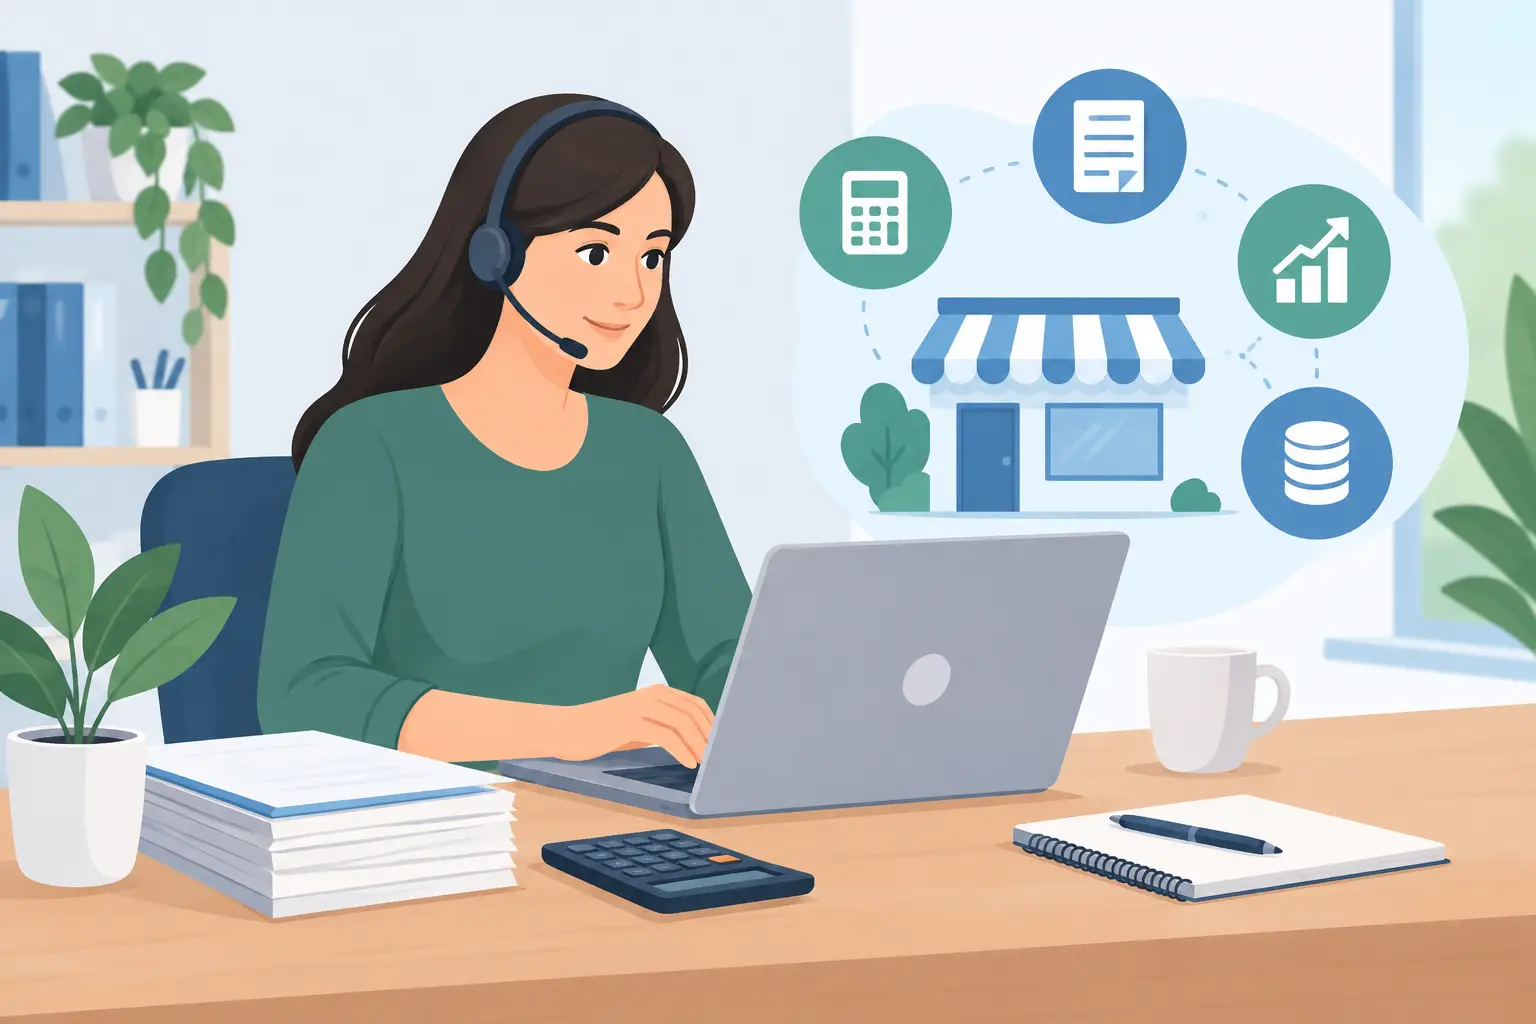
A capable bookkeeping assistant takes ownership of recurring financial administration under your established processes and accountant’s guidance. The work often begins with the tasks that are necessary but easy to postpone: transaction categorization, bank and credit-card reconciliations, invoice tracking, accounts payable support, receipt organization, and monthly reporting preparation.
For a service business, that may mean matching deposits to client invoices and flagging overdue balances before they affect cash flow. For an eCommerce company, it can include organizing sales-channel deposits, tracking merchant fees, and keeping returns visible. A real estate team may need expense coding by property, while an agency may need contractor payments and project costs organized by client.
The scope should reflect the systems you already use. Many assistants work inside QuickBooks Online, Xero, FreshBooks, spreadsheets, bill-pay platforms, and receipt-capture tools. They can also maintain a clean document trail for your CPA. However, business owners should distinguish routine bookkeeping support from licensed tax advice, audit representation, or complex financial planning. Those responsibilities belong with the appropriate accountant or advisor.
Why Small Businesses Benefit From Dedicated Support
The biggest benefit is not simply lower administrative cost. It is better decision-making.
When financial records are current, an owner can see whether margins are holding, whether customers are paying on time, and whether a planned hire is financially sensible. When the books are weeks behind, every decision becomes a guess based on the bank balance. Those are not the same thing.
A dedicated remote professional also protects higher-value time. Owners often spend evenings chasing receipts, correcting categories, or trying to understand why a reconciliation does not balance. Those hours are better spent on client relationships, sales, team leadership, and the work only the owner can do.
Cost matters as well. A full-time domestic hire may not make sense for a company that needs dependable bookkeeping coverage but does not require a controller. Offshore staffing can provide a practical middle ground, particularly for recurring work that demands consistency. Depending on role requirements and experience, businesses may save up to 80% of staffing costs compared with domestic hiring while still building a long-term working relationship.
The trade-off is that savings do not remove the need for management. A bookkeeping assistant needs clear rules, access controls, and regular review. The businesses that get the best results treat the role as a real position with documented responsibilities, rather than a loose collection of tasks sent over whenever something becomes urgent.
How to Hire a Remote Bookkeeping Assistant for Small Business
Start by defining the outcome, not just the job title. “Help with bookkeeping” is too broad to produce a strong hire. Instead, identify the work that needs to happen every week and every month, the software involved, the volume of transactions, and the reports you expect to review.
A clear role might include reconciling three bank accounts every Friday, categorizing transactions according to an approved chart of accounts, preparing an accounts receivable aging report twice a month, and organizing questions for the CPA before month-end close. That level of specificity helps candidates understand the work and helps you evaluate their experience.
Prioritize software knowledge and process discipline
Software familiarity is valuable, but accuracy and judgment matter just as much. Look for a candidate who can explain how they investigate a discrepancy, document an unusual transaction, and escalate an item they are not authorized to decide. A bookkeeper should not quietly guess when a charge is unclear or a payment does not match an invoice.
Ask practical interview questions. How would they handle a duplicated expense in the bank feed? What supporting documents would they request for a large owner reimbursement? How do they prepare a reconciliation for review? Their answers reveal whether they understand control, documentation, and accountability.
Build security into the role from day one
Financial access requires boundaries. Give your assistant access only to the systems and permissions required for their responsibilities. Use unique logins, multifactor authentication, password-management tools, and approval workflows for payments. Avoid sharing personal banking credentials or allowing one person to create vendors, enter bills, and release payments without oversight.
A simple separation of duties can make a meaningful difference. Your assistant may prepare bills and reconciliation reports, while an owner or manager approves payments and reviews exceptions. The goal is not to create friction. It is to create a process that remains trustworthy as the business grows.
When working with an offshore staffing partner, ask how candidates are screened, how work time is verified, and what support exists if performance or communication issues arise. Virtual Coworker, for example, combines candidate screening, background checks, HR and payroll management, and verified time tracking so business owners can focus on selecting and managing the right dedicated teammate.
Create a reliable weekly and monthly cadence
The first 30 days should focus on consistency, not speed. Give the assistant access to documented procedures, your chart of accounts, prior reconciliations, recurring vendor details, and examples of reports you consider useful. Schedule a short weekly check-in to answer questions and review exceptions while the process is still new.
After the first month, establish a standard close routine. The assistant can confirm that accounts are reconciled, outstanding invoices are reviewed, receipts are attached where required, and open questions are compiled for management or the accountant. You can then review a small set of numbers that actually drive decisions: cash on hand, accounts receivable aging, major expense changes, and monthly profitability.
Common Mistakes That Undercut the Investment
The most common mistake is hiring before the business has defined its bookkeeping process. An assistant can improve an imperfect workflow, but they cannot reliably interpret rules that only exist in the owner’s head. If you have inconsistent expense categories or no approval process, document the basics first.
Another mistake is expecting a bookkeeper to solve every finance need. A bookkeeping assistant keeps records organized and reporting timely. They may not be the right person to design a pricing strategy, file complex tax returns, or forecast a capital raise. Clarifying the role protects both quality and compliance.
Finally, do not wait until year-end to review the work. Monthly review is usually enough for many small businesses, though higher-volume operations may need weekly visibility. A regular review catches small issues early and gives your assistant the feedback needed to become more effective over time.
The Right Fit Is Built Around Trust and Visibility
A remote bookkeeping assistant is most valuable when the role gives you a clearer view of the business, not another person to manage. Define the work, establish financial controls, and choose someone who communicates clearly and follows a repeatable process. With the right structure, clean books stop being a year-end scramble and become a dependable operating advantage.
Start with one month of recurring work that you are ready to delegate, document what “done” looks like, and review the results together. That first disciplined handoff often creates the capacity to make smarter decisions long before the next set of financial statements arrives.